Money
House Affordability Calculator
How much house you can afford with your income and your debts
This house affordability calculator works backwards from your debt-to-income ratio: it takes your gross income and your monthly debts and finds the home price whose full payment, with taxes and insurance, fits the limit you choose.
The key idea
What a lender approves is not what you can afford: your other debts come first
With $100,000 of income and a 36% debt-to-income limit, $3,000 a month can go to debts. A $500 car payment leaves $2,500 for the house, and that is about $377,000 of home with $60,000 down at 6.5%. Pay off the car and the same budget reaches about $446,000.
How it is calculated
Lenders look at your debt-to-income ratio (DTI): all your monthly debt payments, including the new mortgage, divided by your gross monthly income. Each loan program and lender sets its own limit; 36% is a common conservative benchmark, and many programs allow more.
Housing payment = gross monthly income × DTI − other monthly debts
We turn that payment into a price: it has to cover principal and interest on the loan (price minus down payment) plus property tax and homeowners insurance. Solving for the price:
Price = (housing payment − insurance + down payment × k) / (k + tax rate / 12)
where k is the monthly payment for each dollar borrowed at your rate and term. Closing costs, PMI, HOA dues and your savings cushion are not included: leave room for them.
Worked example
With $100,000 of gross income ($8,333.33 a month) and a 36% limit, $3,000 a month can go to debts. Minus a $500 car payment, $2,500 is left for the house. With $60,000 down, 6.5% for 30 years, a 1.1% property tax and $1,800 a year of insurance, you could afford about $377,105: a $317,105 loan, with $2,004.32 of principal and interest, $345.68 of property tax and $150 of insurance a month.
Typical cases
How much house you can afford by income
The home price that keeps your housing payment within 36% of gross income, with $50,000 down, no other debts, a 30-year loan, 1.1% property tax and $1,800 a year of insurance.
| Yearly income | At 5.5% | At 6.5% | At 7.5% |
|---|---|---|---|
| $50,000 | $247,764 | $230,200 | $214,900 |
| $75,000 | $361,494 | $333,829 | $309,731 |
| $100,000 | $475,224 | $437,458 | $404,562 |
| $125,000 | $588,955 | $541,087 | $499,393 |
| $150,000 | $702,685 | $644,716 | $594,224 |
| $200,000 | $930,145 | $851,974 | $783,886 |
| $250,000 | $1,157,605 | $1,059,233 | $973,548 |
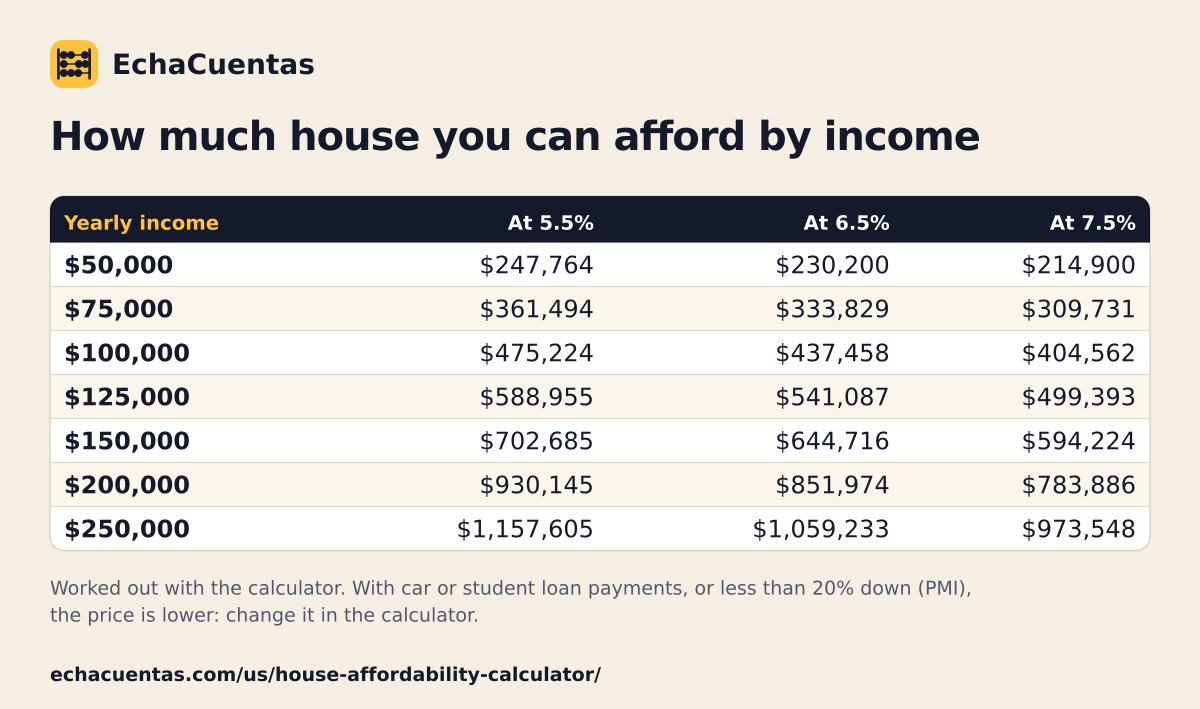 Save or share this table as an image
Common questions
Frequently asked questions
How much house can I afford on $100,000 a year?
Around $377,000 with $60,000 down, a $500 car payment and a 6.5% rate, if you keep all your debts at 36% of gross income. With no other debts, the same income reaches about $446,000.
What is a debt-to-income ratio?
It is all your monthly debt payments divided by your gross monthly income. Paying $2,000 a month in debts on $6,000 of monthly income is a 33% ratio; lenders use it to judge whether you can take on the payment.
What DTI do lenders accept?
It depends on the loan program and the lender. A lower ratio gives you more room in your budget and usually better terms; set the limit you are comfortable with rather than the highest one you could get.
Does my down payment change how much I can afford?
Yes, twice: every dollar down adds a dollar to the price, and a larger down payment lowers the loan and the payment. Putting 20% down on a conventional loan also avoids PMI.
Why is property tax included?
Because it is part of the monthly payment when your lender collects it through escrow. A 1.1% tax on a $377,000 home is about $346 a month, money that cannot go to the loan.
What costs does this leave out?
Closing costs, PMI, HOA dues, maintenance and moving. Keep savings for them on top of the down payment; your Loan Estimate shows the closing costs.
Mortgages, loans and debt
News
Money
You may also need
Your next calculation
Missing a calculator?
Tell us what you need to calculate. The most requested ones are the first we build, with their formula, a worked example and the source.