Money
Mortgage Calculator
Your monthly payment with taxes, insurance and PMI, not just principal and interest
This mortgage calculator gives you the full monthly payment lenders call PITI: principal and interest, property tax, homeowners insurance, plus PMI and HOA dues if you have them, with the total interest and an amortization schedule.
| Year | Interest | Principal | Balance |
|---|---|---|---|
| 1 | $20,695 | $3,577 | $316,423 |
| 2 | $20,455 | $3,816 | $312,607 |
| 3 | $20,200 | $4,072 | $308,535 |
| 5 | $19,636 | $4,636 | $299,555 |
| 10 | $17,861 | $6,410 | $271,284 |
| 15 | $15,407 | $8,864 | $232,189 |
| 20 | $12,014 | $12,257 | $178,129 |
| 25 | $7,322 | $16,949 | $103,373 |
| 30 | $833 | $23,438 | $0 |
The key idea
The payment you are quoted is not the payment you make: taxes and insurance come on top
On a $400,000 home with 20% down at 6.5% for 30 years, principal and interest are $2,022.62 a month. Add $400 of property tax and $150 of homeowners insurance and you pay $2,572.62: 27% more than the number in the ad.
How it is calculated
A fixed-rate mortgage has the same principal and interest payment every month. At first most of it is interest; over the years, more and more goes to principal.
Principal and interest = L × i / (1 − (1 + i)^−n)
L is the loan amount (price minus down payment), i the monthly rate (annual rate / 12) and n the number of payments (years × 12). On top of that, most lenders collect property tax and homeowners insurance each month into an escrow account: together they make up PITI, principal, interest, taxes and insurance.
PMI (private mortgage insurance) is usually required on a conventional loan with less than 20% down; it protects the lender, not you. Its cost appears on your Loan Estimate. For most loans on a principal residence, you can ask to cancel it when your balance is scheduled to reach 80% of the home's original value, and it ends automatically at 78%. FHA and VA loans have their own mortgage insurance or funding fees, not included here.
Worked example
A $400,000 home with $80,000 down (20%) leaves a $320,000 loan. At 6.5% for 30 years, principal and interest are $2,022.62 a month. With $4,800 a year of property tax ($400 a month) and $1,800 of insurance ($150 a month), the payment is $2,572.62. Over 30 years you pay $408,142 of interest.
Official sources
Typical cases
Mortgage payment per $100,000 by rate and term
The monthly principal and interest on each $100,000 you borrow at a fixed rate. For a $300,000 loan, multiply by three.
| Interest rate | 30 years | 20 years | 15 years | 10 years |
|---|---|---|---|---|
| 5% | $536.82 | $659.96 | $790.79 | $1,060.66 |
| 5.5% | $567.79 | $687.89 | $817.08 | $1,085.26 |
| 6% | $599.55 | $716.43 | $843.86 | $1,110.21 |
| 6.5% | $632.07 | $745.57 | $871.11 | $1,135.48 |
| 7% | $665.30 | $775.30 | $898.83 | $1,161.08 |
| 7.5% | $699.21 | $805.59 | $927.01 | $1,187.02 |
| 8% | $733.76 | $836.44 | $955.65 | $1,213.28 |
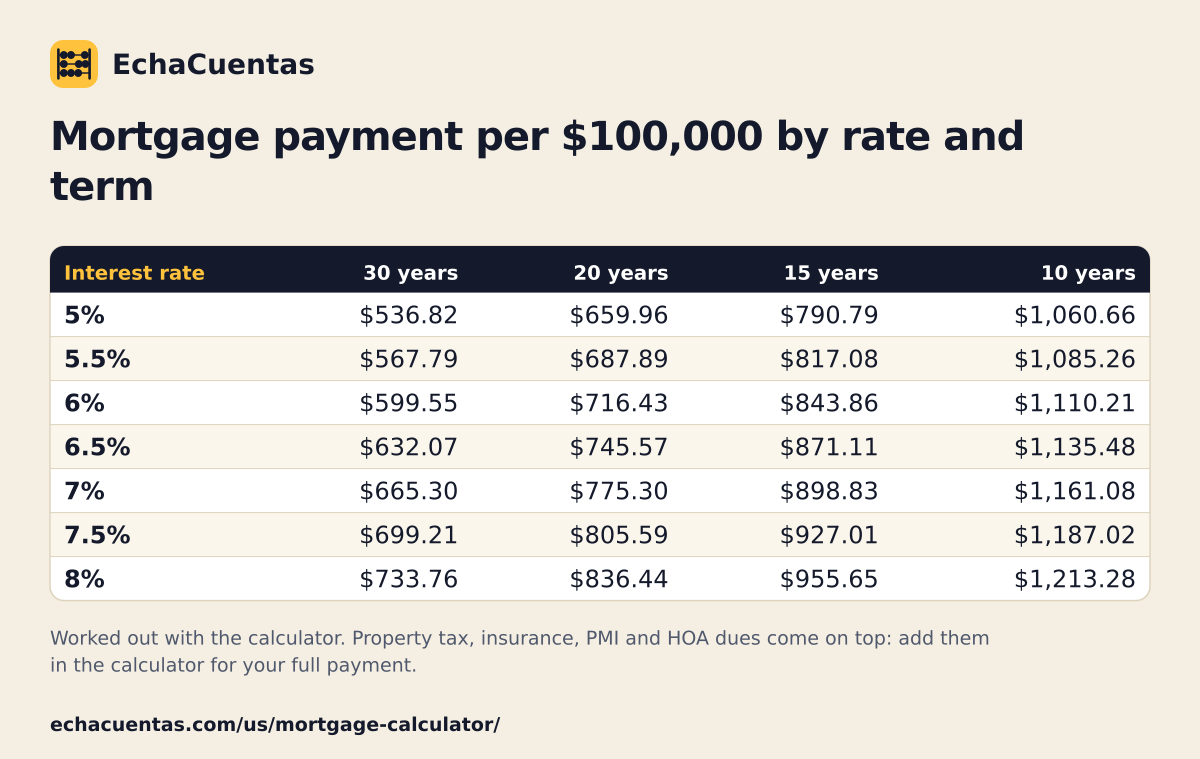 Save or share this table as an image
Common questions
Frequently asked questions
How is a mortgage payment calculated?
With the amortization formula: loan × monthly rate / (1 − (1 + monthly rate)^−number of payments). A $320,000 loan at 6.5% for 30 years is $2,022.62 a month of principal and interest, before taxes and insurance.
What is PITI?
Principal, interest, taxes and insurance: the four parts of a typical monthly mortgage payment. Taxes and insurance are often paid through an escrow account your lender manages, so they come with the payment.
When do I have to pay PMI?
Usually when you put less than 20% down on a conventional loan. It is shown on your Loan Estimate and Closing Disclosure, and it can be removed once you have enough equity; FHA loans use their own mortgage insurance instead.
Is a 15-year mortgage better than a 30-year one?
It costs much less interest but has a higher payment. On $320,000 at the same 6.5%, a 15-year loan is about $2,788 a month against $2,023, but total interest drops from about $408,000 to about $182,000; 15-year rates are often lower too.
Do extra payments save money?
Yes: every extra dollar goes to principal, so you pay less interest and finish earlier. Check that your loan has no prepayment penalty and ask your servicer to apply the extra amount to principal.
Where do I find my property tax and insurance?
Property tax comes from your county or city assessor and depends on the home's assessed value and local rates. Insurance comes from your quote; your Loan Estimate shows the estimated escrow for both.
Mortgages, loans and debt
News
Money
You may also need
Your next calculation
Missing a calculator?
Tell us what you need to calculate. The most requested ones are the first we build, with their formula, a worked example and the source.